How to Transition Your Retirement Plan During a Market Downturn
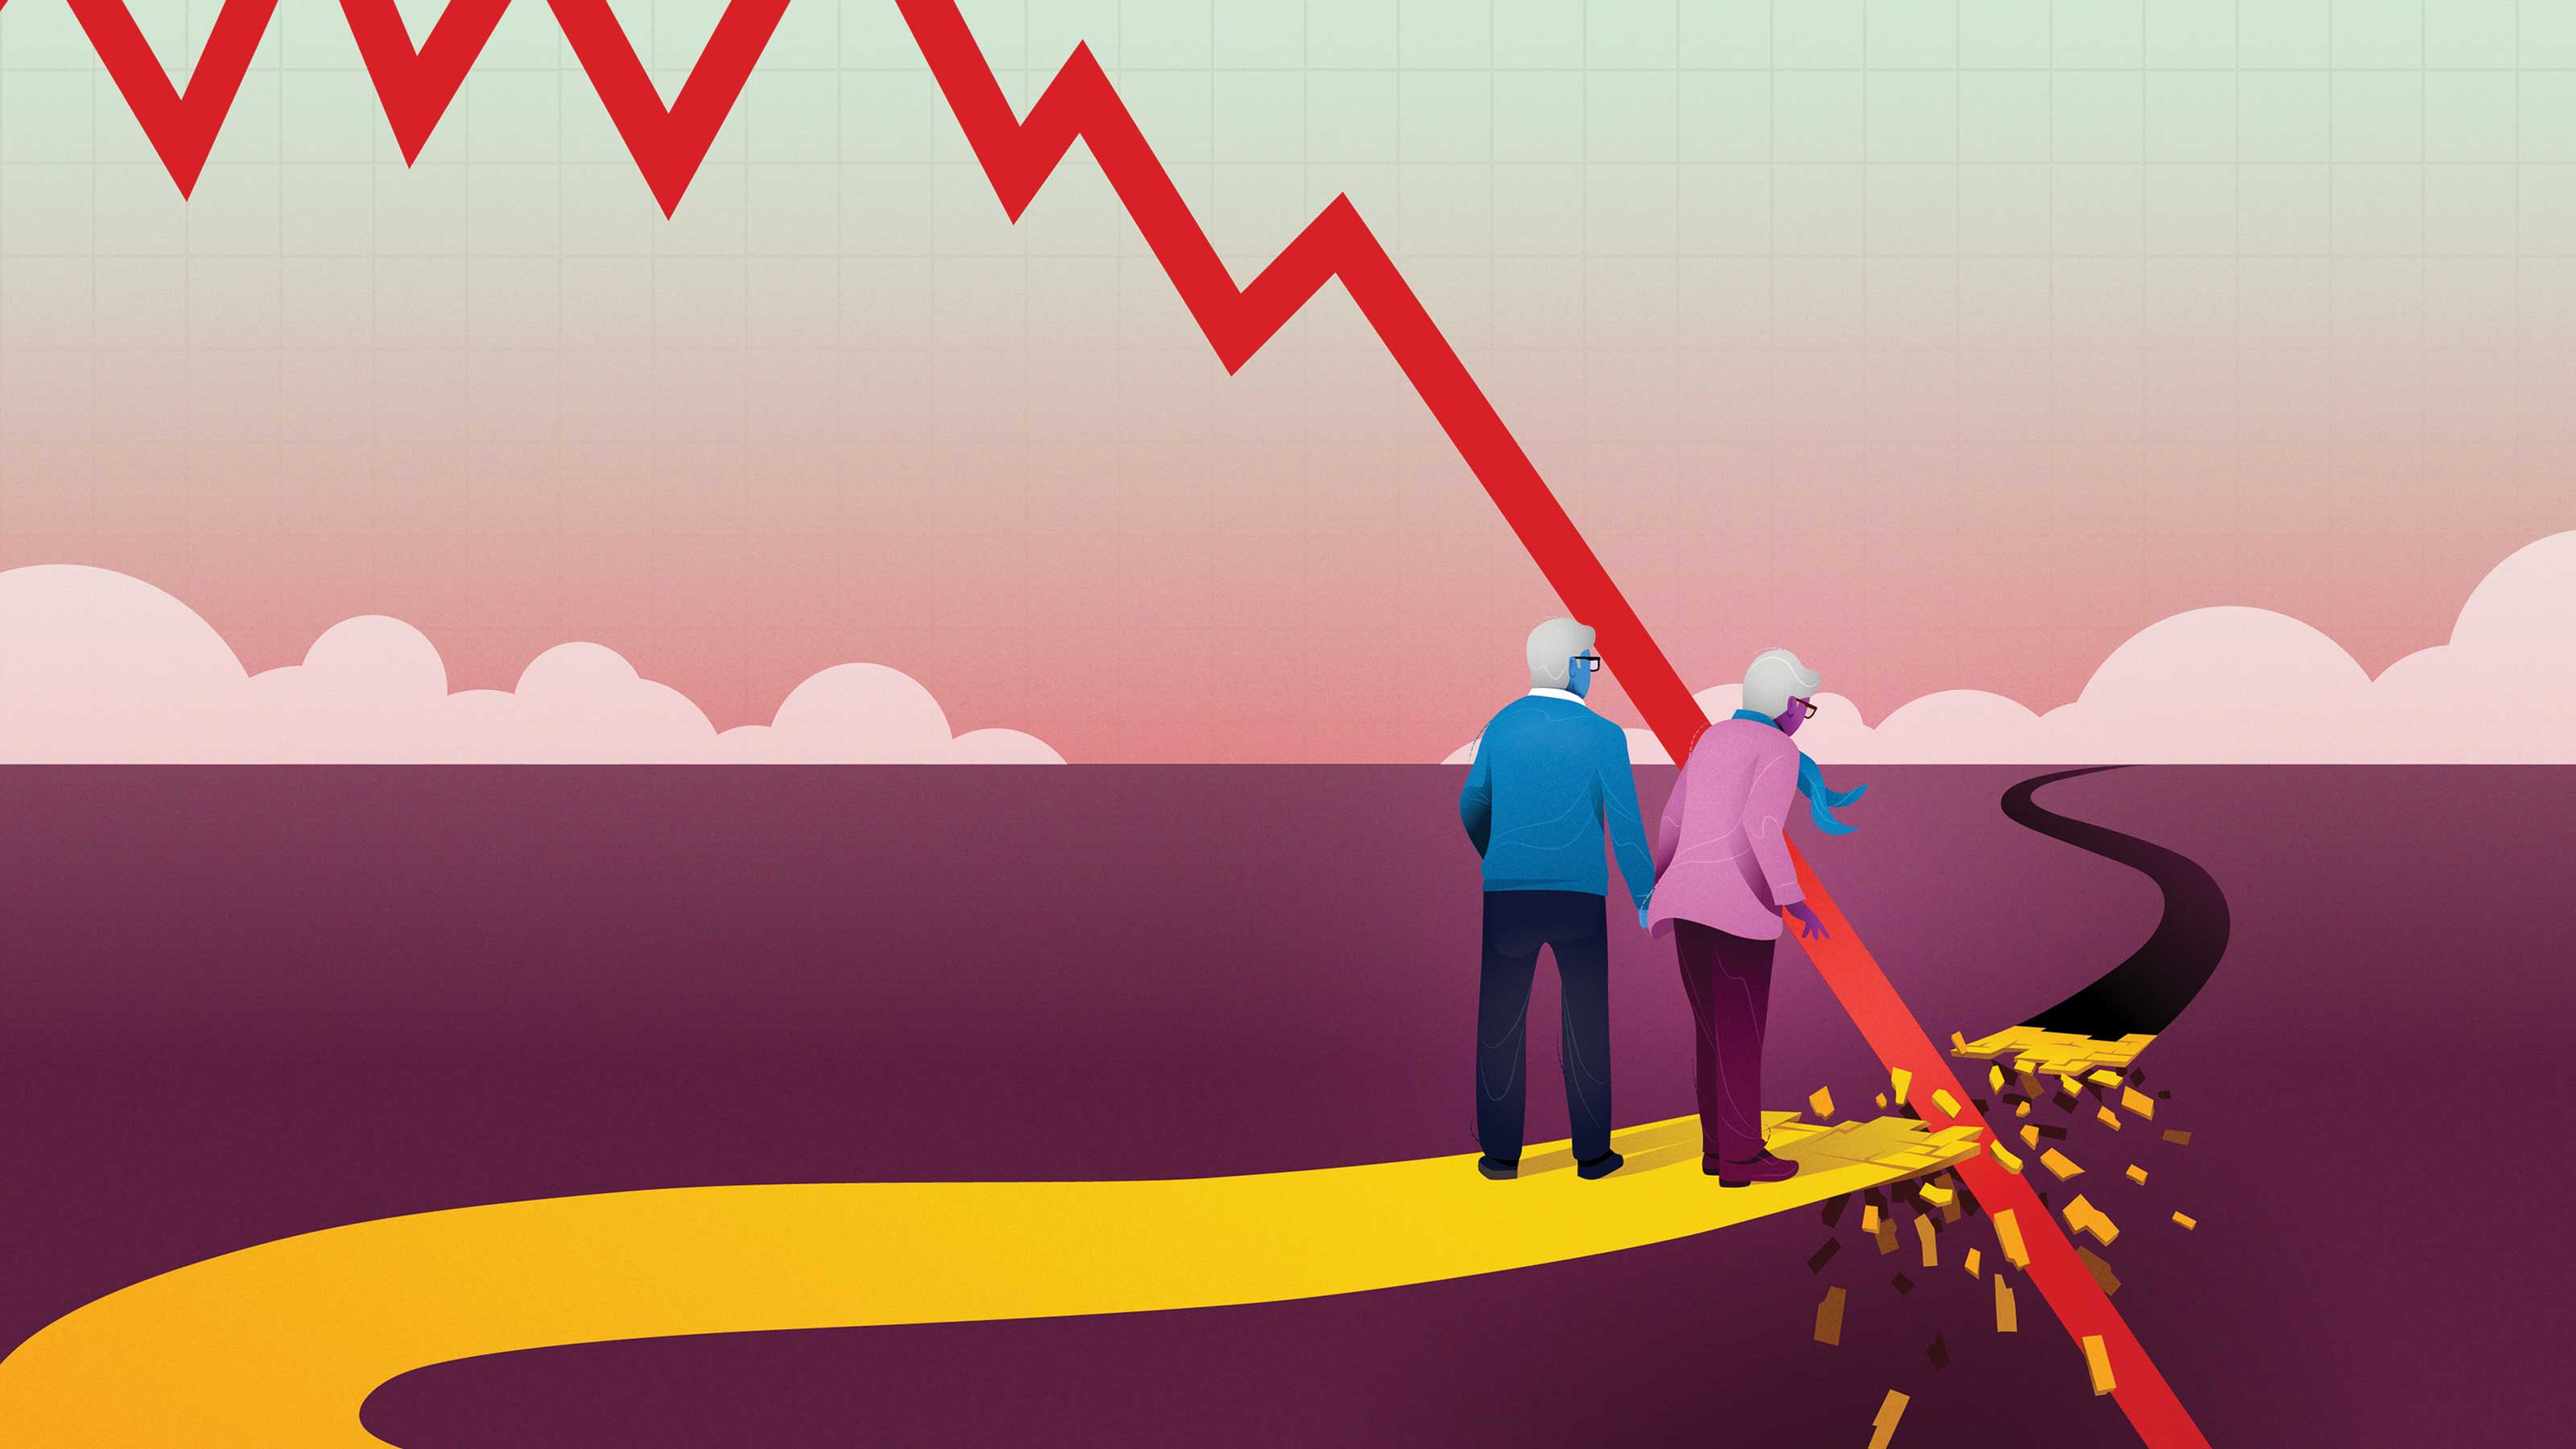
Transitioning your retirement plan during a market downturn requires strategic adjustments that protect your financial security while maintaining long-term growth potential. While market volatility can create significant anxiety for retirees and near-retirees, understanding how to adapt your strategy during challenging periods can mean the difference between depleting your savings prematurely and maintaining financial stability throughout retirement.[1][2][3][4]
Why Market Downturns Demand Strategic Adjustments
Market downturns pose unique challenges for retirees because they combine the worst possible scenario: declining asset values with ongoing withdrawal needs. This combination creates "sequence of returns risk," where poor market performance in the early years of retirement can permanently damage portfolio sustainability. Research shows that negative returns in the first year of retirement can increase the risk of running out of money by 600% over 30 years, making strategic transitions during market volatility crucial for retirement success.[2][3][5]
Understanding the Critical "Danger Zone"
The First Five Years of Retirement
Financial experts identify the initial five years of retirement as a critical "danger zone" where market downturns inflict maximum damage on portfolio longevity. During this period, portfolios are typically at their highest values, making percentage-based losses particularly costly in absolute dollar terms. When you're forced to sell declining assets to meet living expenses, you must sell more shares to generate the same income, leaving fewer assets to participate in eventual market recovery.[3][5][2]
Sequence of Returns Risk in Practice
Consider two identical retirees with $1 million portfolios withdrawing $50,000 annually: one experiencing a 15% market decline in their first year faces dramatically different outcomes than one encountering the same decline later in retirement. The early decline forces the sale of depressed assets, permanently reducing the portfolio's ability to recover even when markets rebound.[5][2]
Strategic Cash Flow Management
The Bucket Strategy for Market Protection
The bucket approach divides retirement assets into time-based segments designed to weather market volatility without forcing asset sales at unfavorable prices. Structure your portfolio with:[4][1]
Near-term bucket (1-3 years): Cash and cash equivalents to cover immediate expenses without touching investments
Medium-term bucket (5-10 years): Fixed-income investments providing moderate returns with less volatility than stocks
Long-term bucket (10+ years): Growth investments positioned for long-term recovery and inflation protection[1][4]
This approach allows you to avoid selling depressed equities during market downturns, giving your growth investments time to recover.[6][4]
Building Adequate Cash Reserves
Financial advisors recommend maintaining 12-24 months of living expenses in cash or cash-equivalent investments during retirement. This buffer prevents forced selling during market declines and provides psychological comfort during volatile periods. For those approaching retirement, having four years' worth of expenses in cash and conservative investments can weather most bear markets, which historically average about 3.5 years for full recovery.[7][6]
Flexible Withdrawal Strategies
Dynamic Spending Adjustments
Rather than rigidly adhering to fixed withdrawal percentages during market downturns, implement flexible spending strategies that reduce distributions during poor market performance. This might involve distinguishing between essential expenses (housing, healthcare, food) that must be maintained and discretionary spending (travel, entertainment) that can be temporarily reduced.[8][9][7]
Alternative Income Sources During Downturns
During market volatility, consider activating alternative income strategies:
Dividend focus: Emphasize dividend-paying stocks that continue generating income despite price volatility[8]
Bond ladders: Structure fixed-income investments to mature regularly, providing predictable income
Part-time work: Even temporary employment can reduce portfolio withdrawal pressure during recovery periods[7]
Strategic Asset Allocation Adjustments
Rebalancing During Volatility
Market downturns often push portfolios away from target allocations, creating rebalancing opportunities. Use systematic rebalancing—perhaps every 6-12 months rather than more frequently—to sell appreciated assets and buy depressed ones without emotional decision-making. This disciplined approach can enhance long-term returns while maintaining appropriate risk levels.[10][11]
Age-Appropriate Risk Management
Consider adjusting equity exposure based on your stage of retirement and market conditions. Some experts recommend the "120 minus your age" rule for stock allocation, while others suggest maintaining 50-55% equity exposure throughout retirement for growth potential. However, recent market volatility may warrant temporary reductions in risk exposure, particularly during the critical early retirement years.[12][10]
Advanced Protection Strategies
Opportunistic Investing During Downturns
Market declines create opportunities to purchase quality investments at reduced prices. If you have adequate cash reserves and don't need to sell investments for income, consider dollar-cost averaging into depressed markets. This strategy can improve long-term portfolio performance by acquiring more shares when prices are low.[11][8]
Professional Guidance and Stress Testing
Working with financial advisors becomes particularly valuable during market transitions. Professionals can help stress-test your retirement plan against various market scenarios, ensuring your strategy can weather extended downturns. They can also provide emotional support during volatile periods, helping you avoid panic-driven decisions that lock in losses.[13][4][11][7]
Most Critical Information
The first five years of retirement represent a "danger zone" where market downturns can inflict permanent damage on portfolio sustainability.[3][5]
Negative returns in early retirement increase the risk of running out of money by 600% over 30 years compared to positive early returns.[3]
The bucket strategy with 1-3 years of expenses in cash prevents forced selling of depressed investments during market downturns.[4][1]
Maintaining 12-24 months of living expenses in cash reserves provides crucial protection during market volatility.[6][7]
Flexible spending strategies that reduce discretionary expenses during downturns can significantly improve portfolio longevity.[8][7]
Systematic rebalancing every 6-12 months during volatility can enhance returns by buying low and selling high.[10][11]
Professional guidance helps maintain discipline and avoid emotional decisions that can lock in permanent losses.[4][7]
Actionable Steps for Market Downturn Navigation
Successfully transitioning your retirement plan during market downturns requires preparation, flexibility, and disciplined execution of proven strategies. To protect your retirement security:[2][4]
Implement the bucket strategy by maintaining 1-3 years of expenses in cash and short-term investments to avoid forced selling during market declines.[1][4]
Build and maintain adequate cash reserves of 12-24 months of living expenses to provide flexibility during extended market downturns.[6][7]
Develop flexible spending strategies that distinguish between essential and discretionary expenses, allowing temporary reductions during poor market performance.[7][8]
Use systematic rebalancing rather than emotional decision-making to maintain target allocations and potentially enhance long-term returns.[11][10]
Consider delaying retirement by 6-12 months if markets remain volatile and you have flexibility, as this can significantly strengthen your financial position.[9][7]
Work with financial professionals to stress-test your plan against various scenarios and maintain discipline during volatile periods.[11][7]
Focus on long-term recovery rather than short-term losses, remembering that historically, diversified portfolios have recovered from all major market downturns.[5][4]
By understanding sequence of returns risk and implementing protective strategies before you need them, you can navigate market downturns with confidence, ensuring your retirement savings last throughout your golden years regardless of market timing.[2][3][4]
__________________________________________________________________________________________________________________________________________________________________________________________________________________________________________________
https://www.ameriprise.com/financial-goals-priorities/investing/retiring-during-challenging-market
https://creativeplanning.com/insights/financial-planning/forces-shaping-retirement/
https://www.cnbc.com/2025/03/25/retirees-protect-portfolios-stock-market-downturn.html
https://www.edelmanfinancialengines.com/education/retirement/retiring-in-a-bear-market/
https://www.fuchsfinancial.com/market-volatility-in-retirement/
https://www.schwab.com/learn/story/market-volatility-retirement-what-if-you-havent-prepared
https://imaginefinancialsecurity.com/financial-planning/bear-market-strategies/
https://www.aol.com/finance/is-this-a-bad-year-to-retire-175930340.html
https://www.prudential.com/financial-education/how-to-fight-a-bear-market
https://www.farther.com/resources/foundations/how-to-protect-401-k-from-stock-market-crash
https://afmfa.com/retirement-planning-for-2025-and-beyond-adapting-to-a-post-pandemic-economy/
https://blog.umb.com/personal-banking-tips-bear-market-retirement/
https://berkshiremm.com/how-a-recession-could-affect-your-retirement-income-plan-and-what-to-do-now/
https://www.morningstar.com/portfolios/age-when-your-retirement-portfolio-should-shift-gears
https://www.mizecpas.com/retirement-planning/protect-your-retirement-accounts/
https://www.nysdcp.com/rsc-preauth/learn-about-retirement/currently-saving/articles/down-market